
Your Capital Has a Speed Limit. Are You Enforcing It?
My career requires precision and efficiency. I expect the same from my capital. Like many of my colleagues in medicine, law, and technology, I was drawn to private equity for its potential for outsized, non-correlated returns. The pitch is compelling: access elite managers who acquire and improve private companies, generating multiples you simply can't find in public markets.
But there’s a critical flaw in this model that is rarely discussed with the urgency it deserves: the profound drag on compounding created by its structure. The traditional 10-year private equity fund model is built for institutional timelines, not for professionals aggressively building wealth during their peak earning years. Your capital is put to work on someone else's schedule, and the opportunity cost is immense.
The J-Curve Is More Than an Inconvenience—It’s a Compounding Killer
Investors in private equity are familiar with the “J-Curve.” It describes the pattern of returns where a fund initially posts negative returns as fees are drawn and investments are made, before (ideally) moving into positive territory as portfolio companies mature and are sold. This is accepted as the cost of doing business.
I see it differently. For the first three to five years of a fund's life, your committed capital is either sitting idle as dry powder or actively generating negative returns on paper. This isn’t just a temporary dip; it is a multi-year period where the power of compounding—the primary engine of wealth creation—is completely disengaged. For a high-earning professional, time is the most valuable and non-renewable asset. Sacrificing half a decade of compounding is a cost few of us can afford.
Why Compounding Is a Function of Velocity
Compounding is typically explained with two variables: rate of return and time. There is a third, equally critical variable: reinvestment frequency, or velocity. A high return realized once a decade is fundamentally different from a good return realized and reinvested multiple times within that same decade.
Consider a simplified model:
- Scenario A: Traditional Private Equity. You invest $100,000. Over 10 years, the fund managers do an excellent job and return a 2.5x multiple. Your $100,000 becomes $250,000. An impressive result on its face. But that capital was locked up for the entire duration.
- Scenario B: Short-Duration Strategy. You invest the same $100,000 into a private credit fund focused on asset-backed loans with an 18-month duration, targeting a 12% annualized return. After 18 months, your principal and interest are returned. You immediately redeploy the full amount into a similar investment.
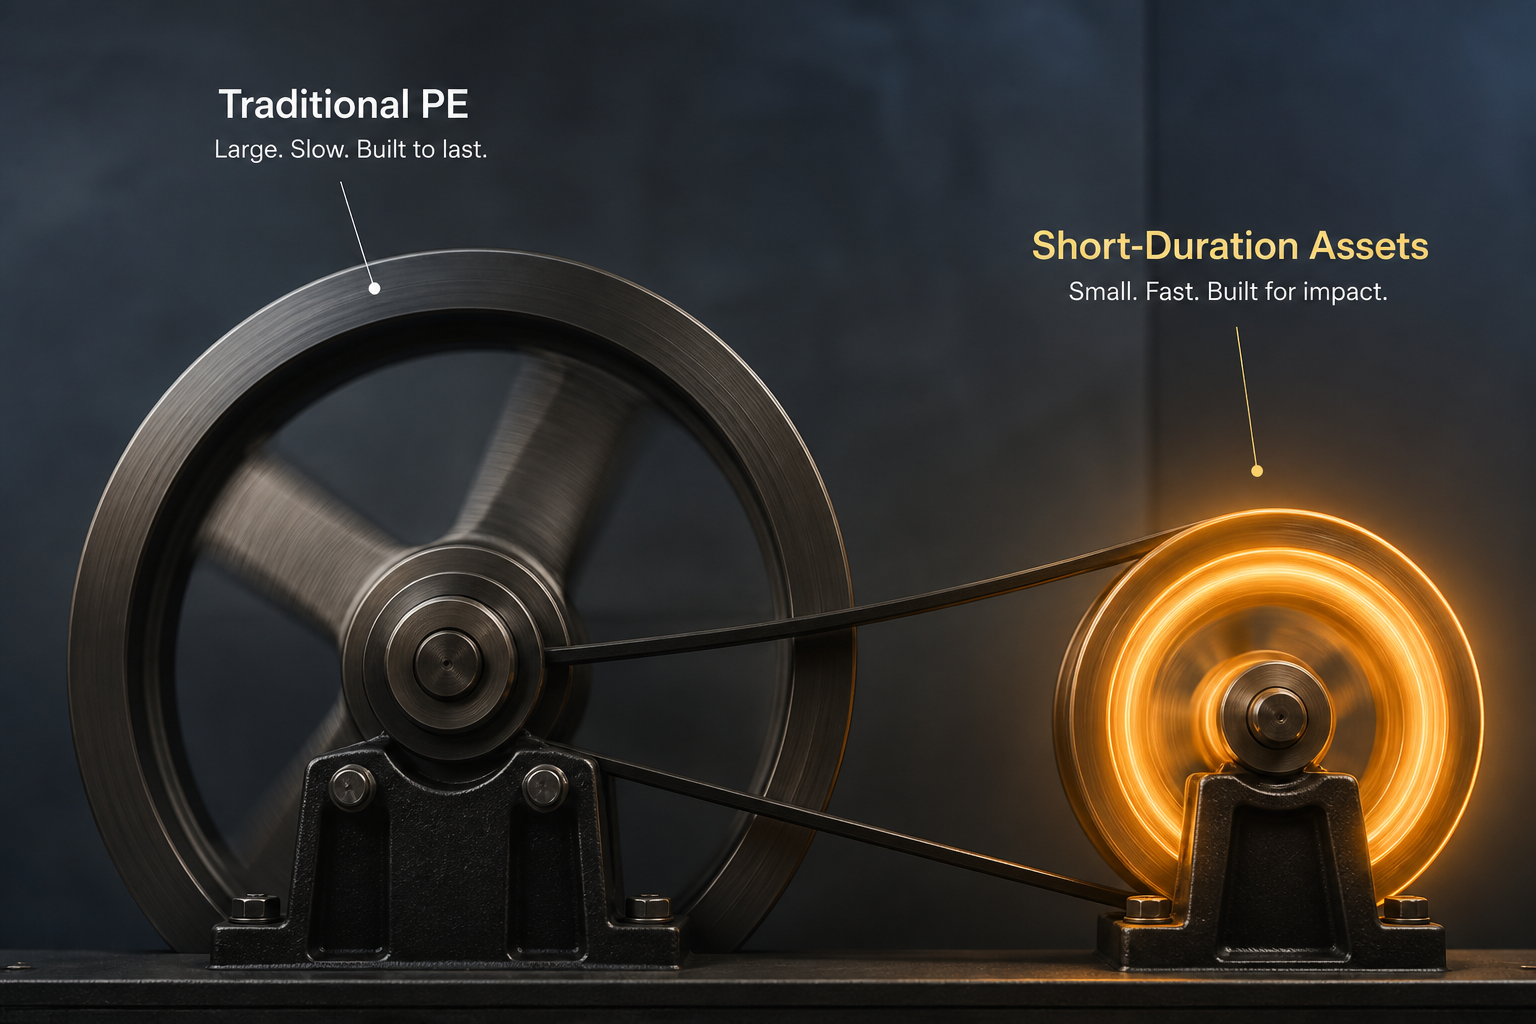
In Scenario B, you are able to cycle your capital more than six times within the same 10-year period. The ability to reinvest not just the principal but the earned returns at frequent intervals creates a dramatically different growth trajectory. The compounding flywheel spins faster, generating returns on top of returns. While the headline multiple of a single deal in PE may look larger, the total wealth generated by the higher-velocity strategy can significantly outpace it over the long term.
Activating Your Capital with Short-Duration Assets
Short-duration alternative assets, particularly in the private credit space, are engineered for this kind of velocity. These strategies often involve lending against hard assets or predictable cash flows, with investment cycles measured in months, not years. Capital is deployed, earns a return, and is returned to the investor, ready for the next opportunity.
This structure offers several distinct advantages for the busy professional:
- Faster Compounding: As illustrated, frequent return of capital allows for rapid reinvestment, accelerating the compounding effect.
- Predictable Income: Many of these strategies are structured to produce regular cash flow in the form of interest payments, creating a reliable passive income stream.
- Reduced Blind Pool Risk: Unlike a 10-year PE fund where you commit capital without knowing the specific future investments, shorter-duration assets often provide more transparency into the underlying collateral from the outset.
The Mandate for Capital Efficiency
I spent over a decade mastering my profession. My investment portfolio needs to work with the same intensity. Letting capital sit idle or unproductive for years inside a J-curve is an unacceptable inefficiency. The goal isn't just to find high-return investments; it's to build a system where capital is constantly in motion, compounding relentlessly while I focus on my career.
Evaluating an investment solely on its projected IRR or final multiple is an incomplete analysis. You must also ask: How quickly can I get my capital back to work? For professionals in their prime wealth-building phase, the answer to that question may be the single most important determinant of long-term success.
This article is for informational and educational purposes only and should not be considered investment, legal, or tax advice. All investment strategies involve risk, and you should consult with a qualified professional before making any financial decisions.
