
The Retirement Income Puzzle I Had to Solve
Like many of you, I did everything by the book. I worked hard, saved diligently, and built a portfolio I thought was ready for retirement. Then I retired, and the reality of the traditional playbook set in. The yields on 'safe' government bonds were barely keeping up with inflation, and the stock market, while great for long-term growth, felt far too volatile to rely on for my monthly grocery bill. My portfolio was built for accumulation, but I needed it to pivot to distribution — to provide reliable, steady income.
I considered becoming a landlord. The idea of monthly rent checks was appealing, but the reality of midnight maintenance calls and tenant turnover was not. My retirement was meant to be a time of freedom, not a second career in property management. I needed an investment that produced real, predictable income without requiring me to watch a screen or answer a phone call every time something went wrong.
Looking Beyond Stocks and Bonds
My search for a better solution led me away from the public markets and toward an area I’d heard about but never deeply explored: private credit. Specifically, a strategy that felt grounded in the real economy: financing small businesses and sharing in their daily revenue.
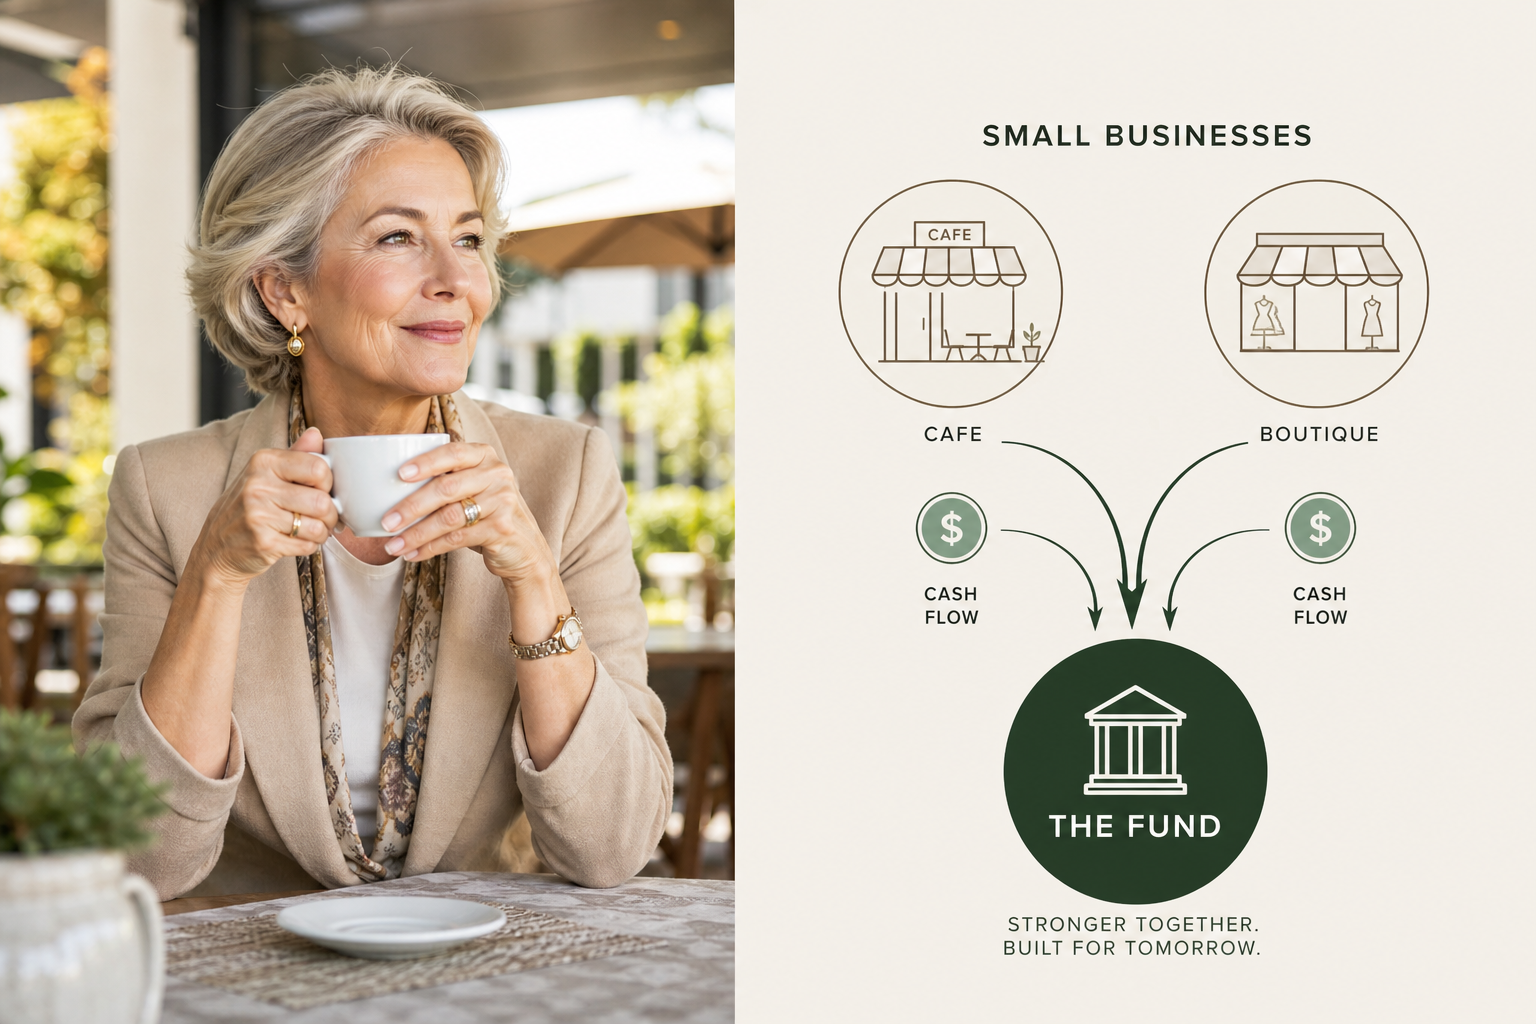
Think about it. Every day, millions of people buy coffee, get a haircut, or have their car repaired. These small and medium-sized businesses are the backbone of our economy, generating consistent sales. What if you could earn income based on that constant activity? Not by owning the businesses, but by providing them with the short-term capital they need to grow, and in return, receiving a small percentage of their daily sales until the financing is repaid.
How Revenue-Based Financing Works for an Investor
In simple terms, this is how it functions from an investor’s perspective:
- You invest in a specialized fund that focuses on this type of private credit.
- The fund’s managers perform due diligence and provide capital to hundreds or thousands of established small businesses across different industries and locations.
- In exchange for the capital, each business agrees to remit a small, fixed percentage of its daily credit and debit card sales.
- These daily remittances flow back to the fund, creating a steady stream of cash.
- The fund then makes regular distributions—often monthly or quarterly—to its investors, like you and me.
The key here is that your return isn’t tied to a company’s stock price or a bond’s interest rate. It’s tied to the top-line revenue of a diverse pool of operating businesses.
Why This Model Appeals to a Retiree
After decades in the corporate world, I was looking for specific characteristics in my income investments. This model checked several important boxes.
- Truly Passive Income: Unlike real estate, there is no direct management required from me. The fund managers handle the sourcing, underwriting, and monitoring of all the businesses. My role is simply to be an investor.
- Diversification from Public Markets: The daily sales of a local pizzeria are driven by its neighborhood customers, not by the daily gyrations of the S&P 500. This provides a layer of diversification that can help smooth out returns in a portfolio.
- Consistent Cash Flow: Because the repayments are collected daily from a large number of sources, the income stream flowing into the fund is remarkably consistent. This is exactly what’s needed to support a retirement lifestyle.
- An Inflation Hedge of Sorts: In an inflationary environment, the price of a cup of coffee or a new set of tires goes up. Since the repayments are a percentage of total sales, as gross revenues rise with inflation, the dollar amount being repaid to the fund can also rise. [VERIFY]
Understanding the Risks
Of course, no investment offering potentially higher returns comes without risk. It's crucial to be clear-eyed about the trade-offs. The primary risk is that a business fails and cannot repay its obligation. This is why diversification within a fund is non-negotiable. By spreading the capital across thousands of businesses in different sectors and regions, the failure of any single one has a minimal impact on the overall portfolio.
Another key consideration is liquidity. Unlike a stock, you cannot sell your position in a private credit fund with the click of a button. These are typically long-term investments. For me, that trade-off was acceptable in exchange for less volatility and a higher income stream for a portion of my portfolio.
Finding this corner of the investment world gave me a sense of security that was missing. I finally felt my portfolio was working for my life — generating income from the everyday economy, allowing me the freedom to enjoy the retirement I worked so hard to build.
This article is for informational purposes only and is not intended as investment, tax, or legal advice. All investments involve risk, including the possible loss of principal. Private investments, such as private credit, involve a high degree of risk, are not liquid, and are suitable only for sophisticated investors.
