The Search for Uncorrelated Yield in a Crowded Field
For serious allocators, private credit has long ceased to be an esoteric niche. It is a core component of institutional and high-net-worth portfolios. However, this mainstream acceptance has led to capital saturation in the most visible sectors, particularly commercial real estate and large-cap direct lending. The consequence is predictable: compressed yields and correlated risks. As I have stated before, the best opportunities are rarely the most crowded. The real work is in identifying assets that generate returns from a fundamentally different economic engine than everything else in the portfolio. That is what real diversification looks like.
This search has led me to a deeper allocation in an often-misunderstood corner of the private credit universe: merchant receivables. This isn't a new invention; businesses have sold future revenues for working capital for decades. What is new is the institutional-grade structure that allows investors to access these cash flows at scale, with professional management and a level of diversification that is difficult to replicate elsewhere.
Deconstructing the Merchant Receivable
At its core, a merchant receivable transaction—often called a Merchant Cash Advance (MCA)—is the purchase of a small, fixed percentage of a business's future credit and debit card sales at a discount. It is crucial to distinguish this from a traditional loan. A loan has a fixed repayment schedule, regardless of the borrower's revenue. If sales decline, the debt service obligation remains, creating potential for default.
A merchant receivable, by contrast, is intrinsically linked to the merchant's top-line performance. Repayments are collected as a percentage of daily sales. If a merchant has a slow week, the repayment amount automatically adjusts downward. This structure creates an alignment between the capital provider and the business that is absent in conventional debt. The source of yield is not an interest rate, but the discount rate (or factor rate) applied to the purchase of those future sales. The return is generated by the difference between the capital advanced and the total receivables collected over time.
The Structural Advantages for an Allocator
My interest in this asset class is not based on a narrative, but on its structural merits within a diversified portfolio. Three characteristics stand out:
1. Granular Diversification
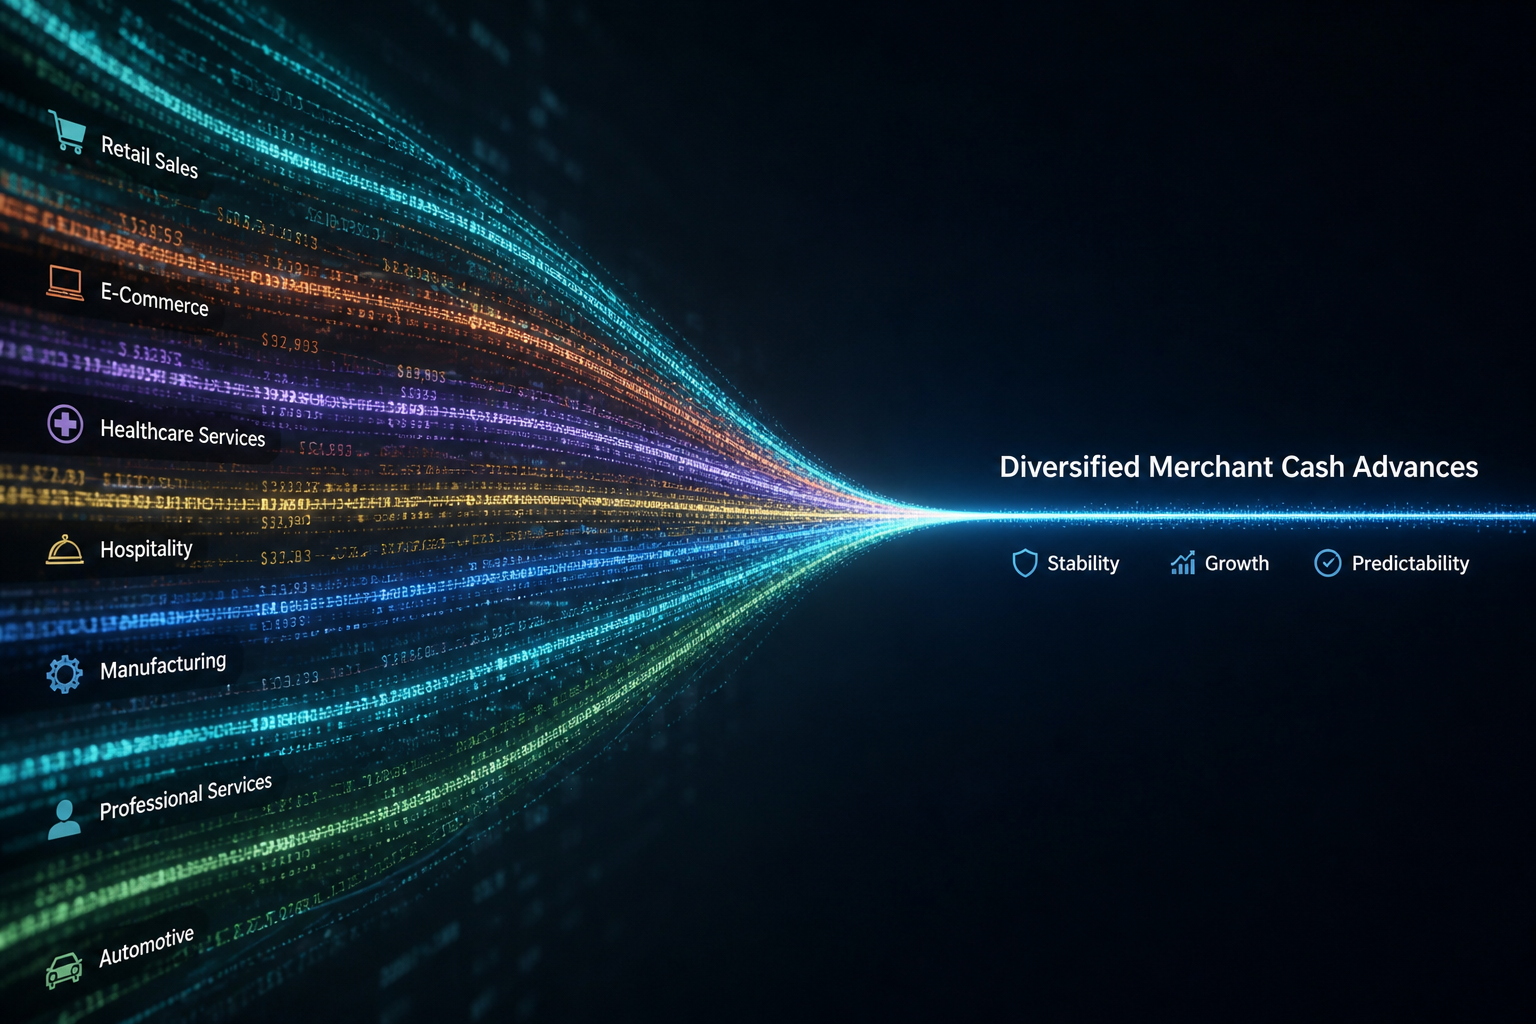
Unlike a CRE debt fund, where exposure might be concentrated across a few dozen properties or sponsors, a merchant receivable fund provides exposure to thousands of small, independent merchants. These are businesses across countless sectors—restaurants, auto repair shops, medical practices, e-commerce stores—and geographies. The failure of any single merchant is a statistically expected event, not a catastrophic loss. This high level of granularity mitigates idiosyncratic risk and produces a more predictable return profile driven by the law of large numbers.
2. Short Duration and Self-Liquidation
The underlying assets are extremely short-term, with typical turnover in 6 to 12 months [VERIFY]. Repayments are not made monthly, but daily, as a direct remittance from the merchant's credit card processor. This creates a constant stream of cash flow back to the fund, which can be redeployed into new receivables. This structure dramatically reduces interest rate sensitivity, a critical attribute in the current macroeconomic environment. While holders of 5-year CRE notes are exposed to duration risk, a merchant receivable portfolio is effectively repricing itself on a continuous basis.
3. A Genuinely Non-Correlated Risk Profile
The primary risk driver for merchant receivables is the operational health of a broad swath of Main Street businesses. This is fundamentally different from the risks that dominate public markets or other private credit strategies. It is not directly tied to interest rate fluctuations, public equity sentiment, or the cap rates of Class A office buildings. While a severe, systemic recession would certainly impact performance, the risk is not correlated to the same factors as the rest of my portfolio. It is a pure play on a segment of the economy that is otherwise very difficult to access.
A Note on Diligence
This is not to suggest the asset class is without risk. The opportunity is not in funding individual businesses but in accessing a professionally managed portfolio. Diligence must be focused squarely on the manager, or what is often called the "originator." A superior operation will leverage sophisticated data science for merchant underwriting, analyzing daily sales data, seasonality, and industry trends to make informed funding decisions. They must also have a robust and scalable servicing infrastructure to manage the complexity of collecting and processing thousands of micro-transactions every day.
Ultimately, merchant receivables represent a compelling allocation for investors seeking to move beyond crowded markets. It offers a structurally sound, short-duration, and genuinely diversified stream of returns. This is not a hot tip, but an observation on where intelligent capital can find a structural edge. For those of us building resilient, all-weather portfolios, it is an area that warrants serious consideration.
This article is for informational purposes only and does not constitute investment, legal, or tax advice. The author holds positions in assets discussed. All investment strategies involve risk, including the possible loss of principal.
