The Only Question That Matters
When I evaluate an investment, I look past the projected yield. The number that matters more is the one that is never advertised: the probability of permanent capital loss. Anyone can generate a high return by taking an commensurate risk. The art of intelligent capital allocation, however, lies not in chasing yield but in constructing systems that are designed to preserve the principal. This is the fundamental difference between speculation and investment, and it is the lens through which I analyze any private market opportunity, including the Salvare Fund's strategy in merchant receivables.
The core proposition of merchant receivables is compelling because it is tied to an elemental economic activity: the daily revenue of operating businesses. The return is not generated by market sentiment or multiple expansion, but by the sale of goods and services. Yet, this direct link to commerce also introduces idiosyncratic risks. The critical question, therefore, is not whether risk exists, but how it is managed. A serious investor must look under the hood at the architecture of risk mitigation.
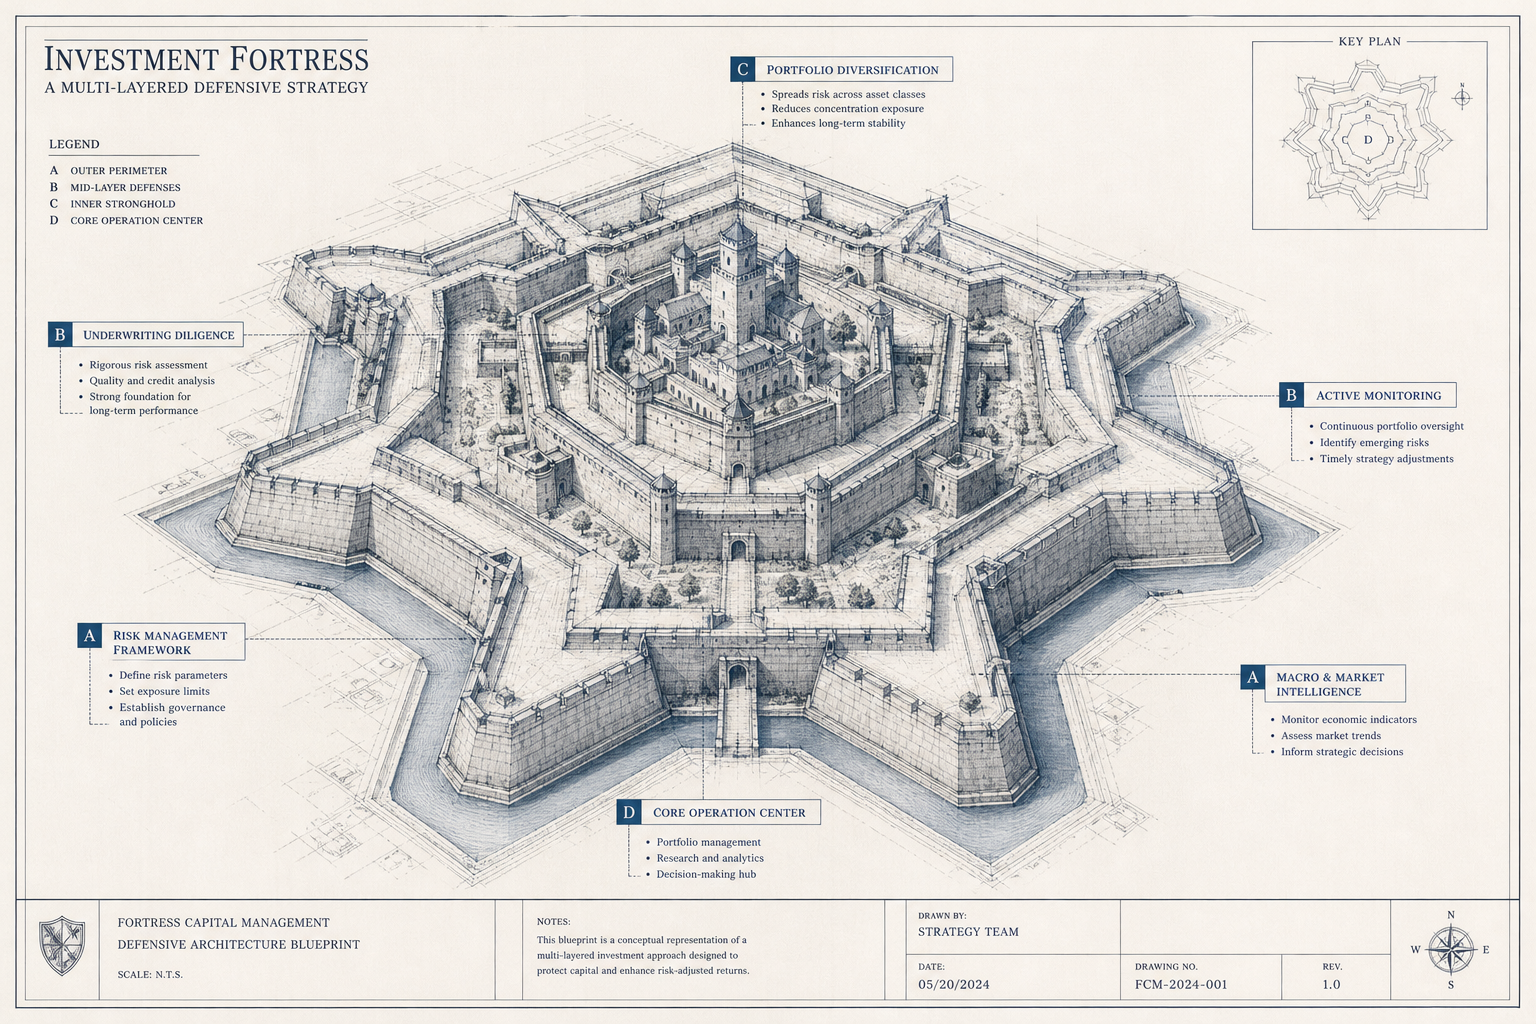
First Pillar: Underwriting as a Filter
Capital preservation begins before a single dollar is deployed. It begins with underwriting. In the context of merchant receivables, this means a rigorous evaluation of the underlying businesses whose future revenue streams are being purchased. Hype and narrative have no place here; only data and operating history matter.
A disciplined underwriting process functions as a critical filter. It assesses factors such as:
- Operating History: How long has the business been operating? Businesses with a track record through multiple economic seasons demonstrate a resilience that is difficult to fake.
- Revenue Consistency: Are the sales patterns stable and predictable, or are they volatile and seasonal? Consistent cash flow is the bedrock of this asset class.
- Industry and Sector: Is the business in a durable sector, or is it subject to transient trends? A focus on non-discretionary goods and services provides a structural defense.
This is not a passive process. It is an active, judgment-based selection that weeds out weaker operators and concentrates capital in businesses with demonstrated durability. This is the first and perhaps most important layer of defense.
Second Pillar: Portfolio Construction as a Moat
Even the most durable single business carries concentration risk. The second pillar of risk management is therefore the deliberate construction of a diversified portfolio. Most people think diversification means owning many different stocks. I think diversification means owning assets that earn money for completely different reasons, and within an asset class, it means insulating the whole from the failure of any single part.
In the Salvare Fund, this is achieved by aggregating a large number of receivables from a wide array of merchants. This diversification is multi-faceted:
- Across Merchants: The failure of any single merchant has a mathematically insignificant impact on the total portfolio's cash flow.
- Across Geographies: Economic activity is distributed across different regional markets, mitigating the impact of a localized downturn.
- Across Industries: A portfolio spread across restaurants, auto repair, healthcare, and other sectors is not dependent on the fortunes of a single industry.
This is not merely a collection of assets; it is a system designed for resilience. The portfolio itself becomes a structural moat protecting investor capital.
Third Pillar: The Structural Advantage of the Asset
Beyond underwriting and diversification, the very structure of a merchant receivable offers an intrinsic risk management advantage. Unlike a traditional term loan where payments are made monthly and problems may fester unseen, merchant receivables are typically collected as a small, fixed percentage of daily credit card sales.
This mechanism provides two key benefits:
- Real-Time Performance Data: The daily remittance stream is a live indicator of a merchant's business health. Any significant deviation is an immediate red flag, allowing for proactive management rather than reactive damage control.
- Self-Adjusting Payments: Because remittances are tied to sales volume, they naturally adjust to the ebbs and flows of the business. During a slow week, the payment is smaller, placing less stress on the merchant and reducing the likelihood of a default cascade.
This structure embeds transparency and flexibility directly into the asset, providing a layer of protection that many other forms of private credit lack.
Discipline is the Strategy
Investing in private markets requires a shift in mindset from seeking alpha to managing risk. High yields are attractive, but sustainable cash flow from durable assets is what builds and preserves dynastic wealth. The Salvare Fund's approach to merchant receivables exemplifies this philosophy. The strategy is not the asset itself, but the disciplined process of selection, diversification, and active management that surrounds it. For investors who have already won the game, this focus on the architecture of capital preservation is the only approach that makes sense.
