
The Crowded Room in Private Credit
As an asset class, private credit has come of age. The illiquidity premium and secured positions have attracted institutional and private capital alike, and for good reason. For years, a significant portion of my own allocation has been in private real estate debt, funding transitional assets and capturing yield outside the public markets. The logic was, and remains, sound. But the first question a serious allocator must always ask is not “What is working?” but “What is becoming crowded?”
Today, capital has flooded the commercial real estate credit space. Competition has compressed yields, and a singular, systemic risk factor—the fate of the commercial property market—underpins the vast majority of these portfolios. While I am not abandoning the sector, I believe the search for alpha requires us to look for fundamentally different economic engines. True diversification is not found by adding another asset tethered to the same macro cycle. It is found in asset classes that generate returns from a distinct and uncorrelated source.
Defining the Asset: More Than a Cash Advance
This is why I have spent the last eighteen months diligencing and building a position in merchant receivables. This is not a new concept; businesses have sold future revenues for working capital for decades. What is new is the institutional-grade infrastructure that now allows allocators to access this cash flow stream at scale.
To be precise, this is not a loan. It is the purchase of a future asset—a specified portion of a business’s future debit and credit card receivables—at a discount. A capital provider advances funds to a small business. In return, the provider receives an agreed-upon percentage of the merchant’s daily card sales until the total purchased amount is collected. The repayment schedule is organic, flexing with the merchant's daily sales volume. This structural detail is critical; it aligns the interests of the capital provider and the merchant in a way a fixed-payment loan does not.
The Structural Advantages Over Traditional Private Credit
The intellectual appeal of this asset class lies in three distinct structural characteristics that are difficult to replicate in real estate or corporate direct lending.
1. Radical Diversification and Granularity
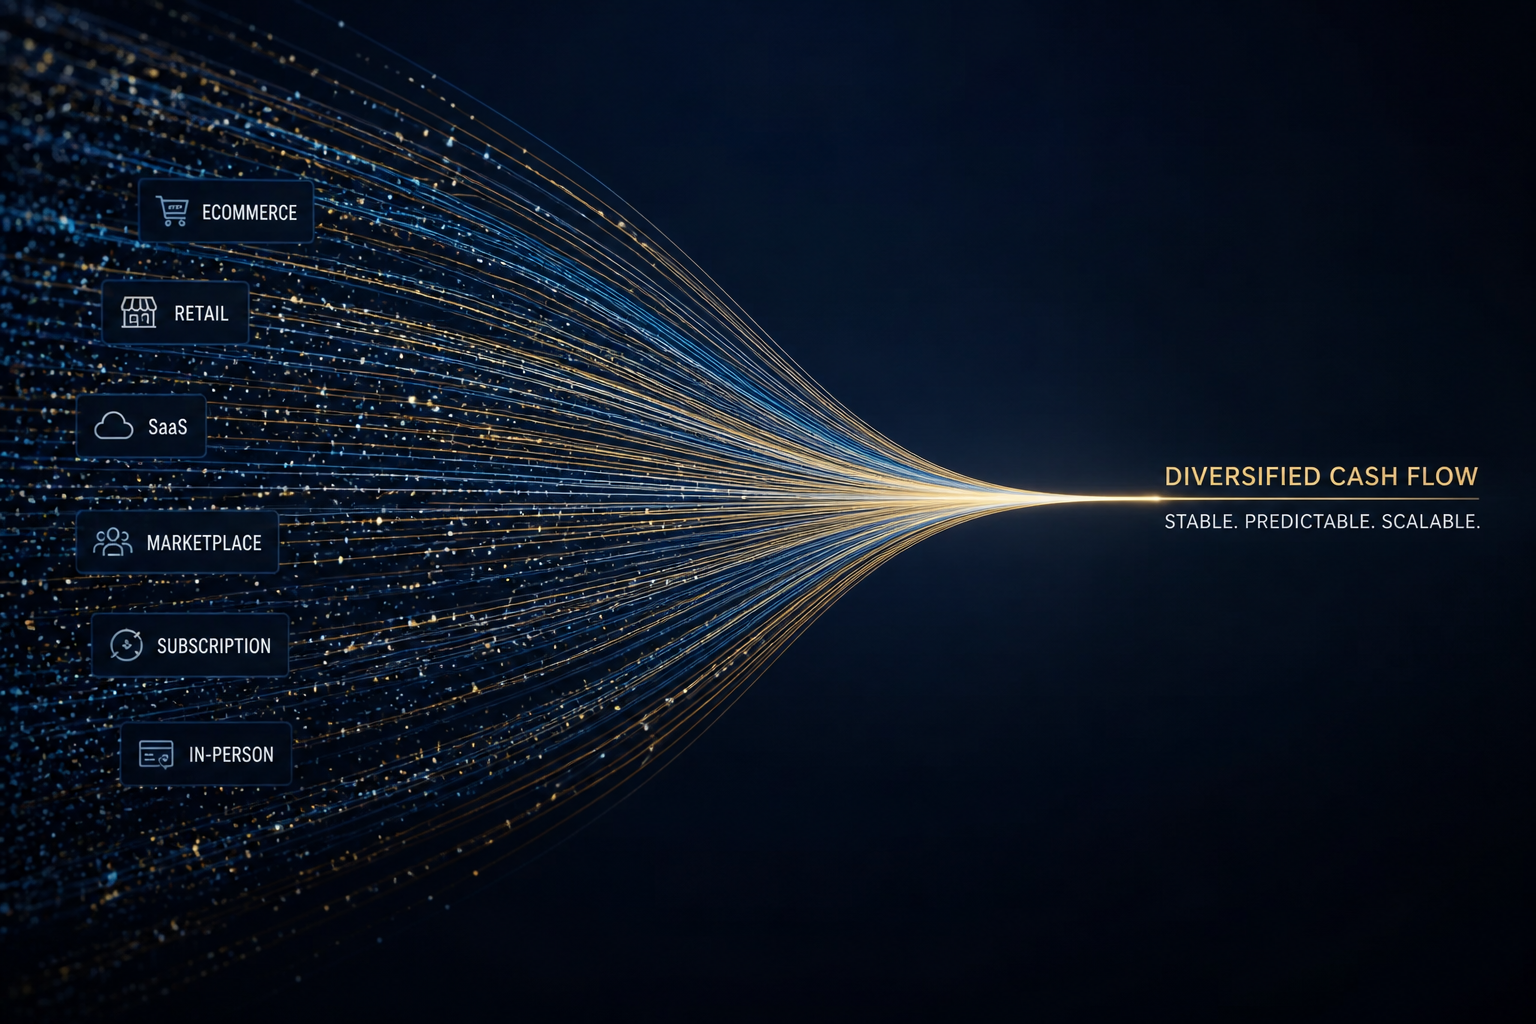
A typical real estate credit fund may hold positions in dozens of properties. An investment in a professionally managed merchant receivables portfolio provides exposure to the daily sales of thousands, or even tens of thousands, of underlying small businesses. These merchants are diversified across uncorrelated sectors—restaurants, auto repair shops, medical offices, retail—and spread across every geography. The performance driver is not the valuation of a single office building but the broad health of Main Street consumer spending. The failure of any single merchant becomes a statistical rounding error, not a portfolio-level event.
2. Extremely Short Duration and Self-Liquidation
The assets are inherently short-term and self-liquidating. Capital is returned daily, and the average life of a receivable purchase is typically under a year [VERIFY]. Compare this to a three-to-five-year bridge loan on a commercial property. This dramatically reduces duration risk, a factor of increasing importance in a volatile interest rate environment. The velocity of capital allows for faster compounding and a more nimble response to changing market conditions.
3. A Genuinely Uncorrelated Return Stream
The cash flows from a diversified pool of merchant receivables are not directly correlated to public equity performance, interest rate movements, or real estate cap rates. While a severe, widespread recession would certainly impact consumer spending, the day-to-day performance is driven by a different set of microeconomic factors. It is a pure play on the transactional economy. Adding an asset class with a truly different return driver is the entire purpose of portfolio construction.
A Clear-Eyed View on Risk
This is not a risk-free asset. The primary risk is, of course, merchant default. However, this is managed at the institutional level through rigorous, data-driven underwriting and the radical diversification discussed above. Sophisticated platforms analyze years of a merchant’s payment processing history to underwrite the stability of their cash flows. This is followed by the daily, technology-enabled monitoring of receipts. It is a level of granularity and real-time data that is simply unavailable in traditional private lending.
Conclusion: An Intelligent Allocation for the Next Cycle
I do not add asset classes to my portfolio because they are novel. I add them when they offer a structural edge. Merchant receivables provide an opportunity to finance a fundamental economic activity—daily commerce—at a scale and with a risk-management framework that was previously inaccessible. As other areas of private credit become commoditized, the ability to source yield from a genuinely different engine is, to my mind, the most intelligent allocation a private investor can make today.
This article is for informational purposes only and does not constitute investment advice. The author holds a position in assets discussed. All investments involve risk, including the possible loss of principal. Private investments are illiquid and not suitable for all investors.
