
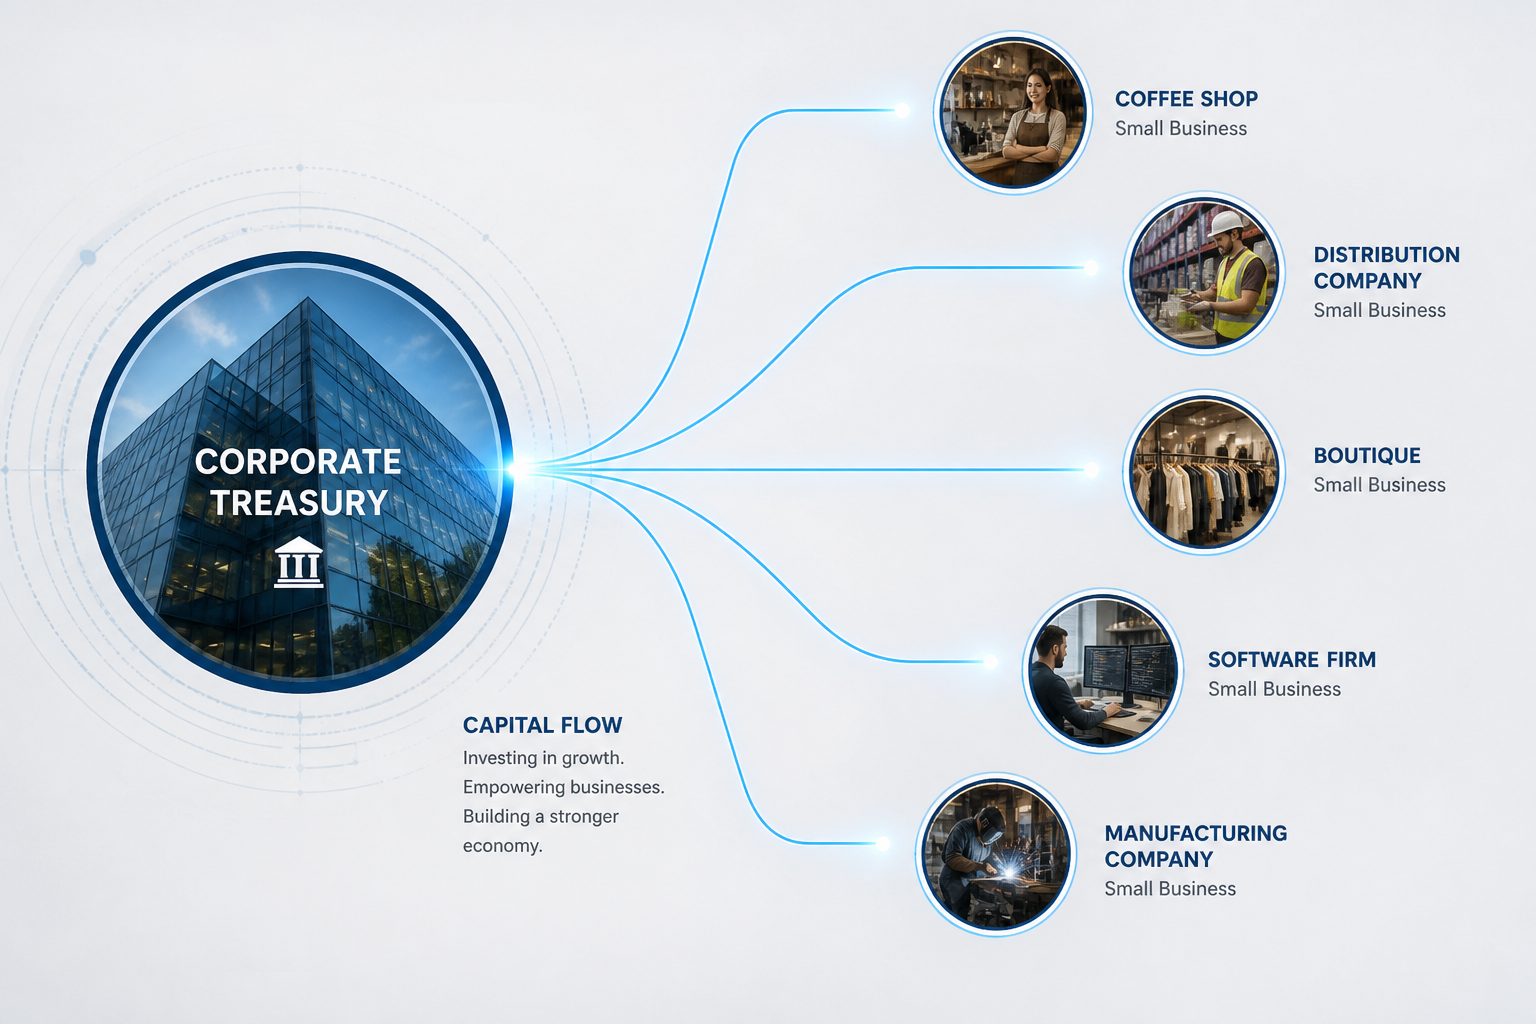
From Idle Cash to Active Capital: An Introduction to the MCA Market
For many successful operating businesses, a comfortable cash reserve is a sign of health. But in a low-interest-rate environment, that cash sitting in a corporate bank account often does little more than lose value to inflation. This has led many business leaders to look for alternative strategies to put their treasury funds to work. One such strategy, typically reserved for sophisticated investors, is entering the Merchant Cash Advance (MCA) market.
This isn't about traditional stock and bond investing. It's about taking on a more active role as a capital provider to other small businesses. For the right company, it can be a way to generate significant returns, but it comes with a unique set of risks and operational demands. Let's break down what it means to deploy corporate cash in the MCA space.
What Exactly is a Merchant Cash Advance?
Before considering an investment, it’s crucial to understand the product itself. A Merchant Cash Advance is not a loan. Instead, it is a commercial transaction where a finance company purchases a portion of a business's future sales at a discount.
Here’s a simple breakdown:
- The Advance: A business receives a lump sum of cash upfront.
- The Purchase: In return, the MCA provider buys, for example, $13,000 of the business’s future revenue for a price of $10,000.
- The Repayment: The MCA provider collects a small, fixed percentage of the business’s daily credit and debit card sales until the full $13,000 is collected.
Because repayment is tied to sales volume, the payment amount flexes with the merchant’s daily cash flow. If sales are slow, the daily payment is smaller; if sales are strong, it's larger. This structure is often appealing to businesses with fluctuating revenue, like restaurants or retailers, which is why they are common MCA clients.
The Appeal vs. The Reality: High Returns and High Risks
The primary attraction for investors in the MCA market is the potential for high, short-duration returns that are largely uncorrelated with public equity and debt markets.
The Potential Upside:
- High Yields: The implied rates of return on successful advances can be significantly higher than those found in traditional fixed-income investments.
- Short Durations: Most advances are collected over a period of a few months to a little over a year, meaning capital is recycled relatively quickly.
- Market Diversification: Returns are tied to the performance of small businesses, not the S&P 500.
The Significant Downsides:
This potential for high returns comes with a commensurate level of risk. The businesses seeking MCAs are often unable to secure traditional bank financing, which inherently makes them a riskier cohort.
- Default Risk: The single greatest risk is merchant default. If the business fails, the investor can lose their entire principal. Default rates in this sector are considerably higher than in traditional lending.
- Regulatory Scrutiny: While MCAs are legally structured as commercial purchases, regulators are increasingly paying attention to the industry. Future changes in regulation could impact the business model.
- Operational Complexity: Properly underwriting, servicing, and collecting on these advances requires specialized expertise and infrastructure.
Two Paths to Participation: Direct Funding vs. Syndication
A company looking to deploy capital in this space generally has two options, each with different levels of involvement and control.
1. Direct Funding
This involves building out an entire MCA funding operation. Your company would be responsible for sourcing merchants, performing due diligence (underwriting), drafting legal agreements, servicing the advances, and managing collections. This path offers the highest potential returns and full control, but it is effectively launching a new, highly specialized financial services business. It requires significant investment in technology, personnel (underwriters, collectors), and legal expertise.
2. Investing with a Partner (Syndication or a Fund)
A more common approach for a corporate investor is to partner with an established MCA company or invest in a fund that specializes in this asset class. In this model, you provide the capital, and the partner manages all the operations. This is a more passive approach that allows you to gain exposure without building the infrastructure. However, you will pay management fees or share a portion of the returns, and you are relying entirely on the partner's expertise and diligence. Choosing the right partner is paramount.
Final Considerations
Deploying excess corporate cash into the MCA market is a sophisticated strategy that moves a company from a pure operator to an active investor. It should not be entered into lightly. Before proceeding, any organization must conduct extensive due diligence, assess its true tolerance for risk, and consult with legal and financial professionals.
While the potential for outsized returns exists, the path is fraught with risk. Success requires deep expertise, robust risk management, and a clear understanding of the unique dynamics of the small business funding landscape.
This article is for informational and educational purposes only and should not be considered investment, legal, or financial advice. The Merchant Cash Advance market involves a high degree of risk, including the potential loss of principal. Consult with qualified professionals before making any investment decisions.
