
The Search for Uncorrelated Alpha
In any market cycle, but particularly in the current environment, the central challenge for a serious allocator is the sourcing of genuinely uncorrelated returns. The public markets, for all their liquidity, have become an exercise in factor-chasing, with correlations that tend to converge toward one precisely when diversification is needed most. My own portfolio construction philosophy is built on a simple premise: I seek to own assets whose performance is driven by fundamentally different economic engines. This is the only path to building a resilient, all-weather allocation.
This search often leads us to private markets, but even there, a discerning eye is required. Much of what is labeled “alternative” is simply leveraged public market exposure with a liquidity premium. The real opportunity lies in finding assets that are not just private, but structurally distinct. Merchant receivables, an often-misunderstood corner of the private credit universe, represent one such opportunity for those willing to perform the necessary diligence.
Deconstructing the Asset: More Than a Loan
At its core, a merchant receivable is not a loan, but the purchase of a future asset—a specified portion of a business’s future revenue—at a discount. An investor provides working capital to a small or medium-sized business (SMB) today in exchange for the right to collect a small, fixed percentage of that business’s daily credit and debit card sales until a predetermined amount has been received.
The distinction from traditional debt is critical. There is no fixed term, no set monthly payment, and no compounding interest in the conventional sense. Repayment is directly tethered to the merchant's top-line revenue. If sales are strong, the receivable is collected faster; if the business experiences a slow period, the collection period extends. This creates a self-liquidating, short-duration asset whose performance is tied to the daily rhythms of consumer spending, not to the machinations of the capital markets.
The Structural Edge for Allocators
What makes this structure compelling is not the novelty of the idea—factoring receivables is an age-old practice—but its characteristics at a portfolio level when accessed through a professionally managed, institutional-grade vehicle. The value proposition rests on several key pillars:
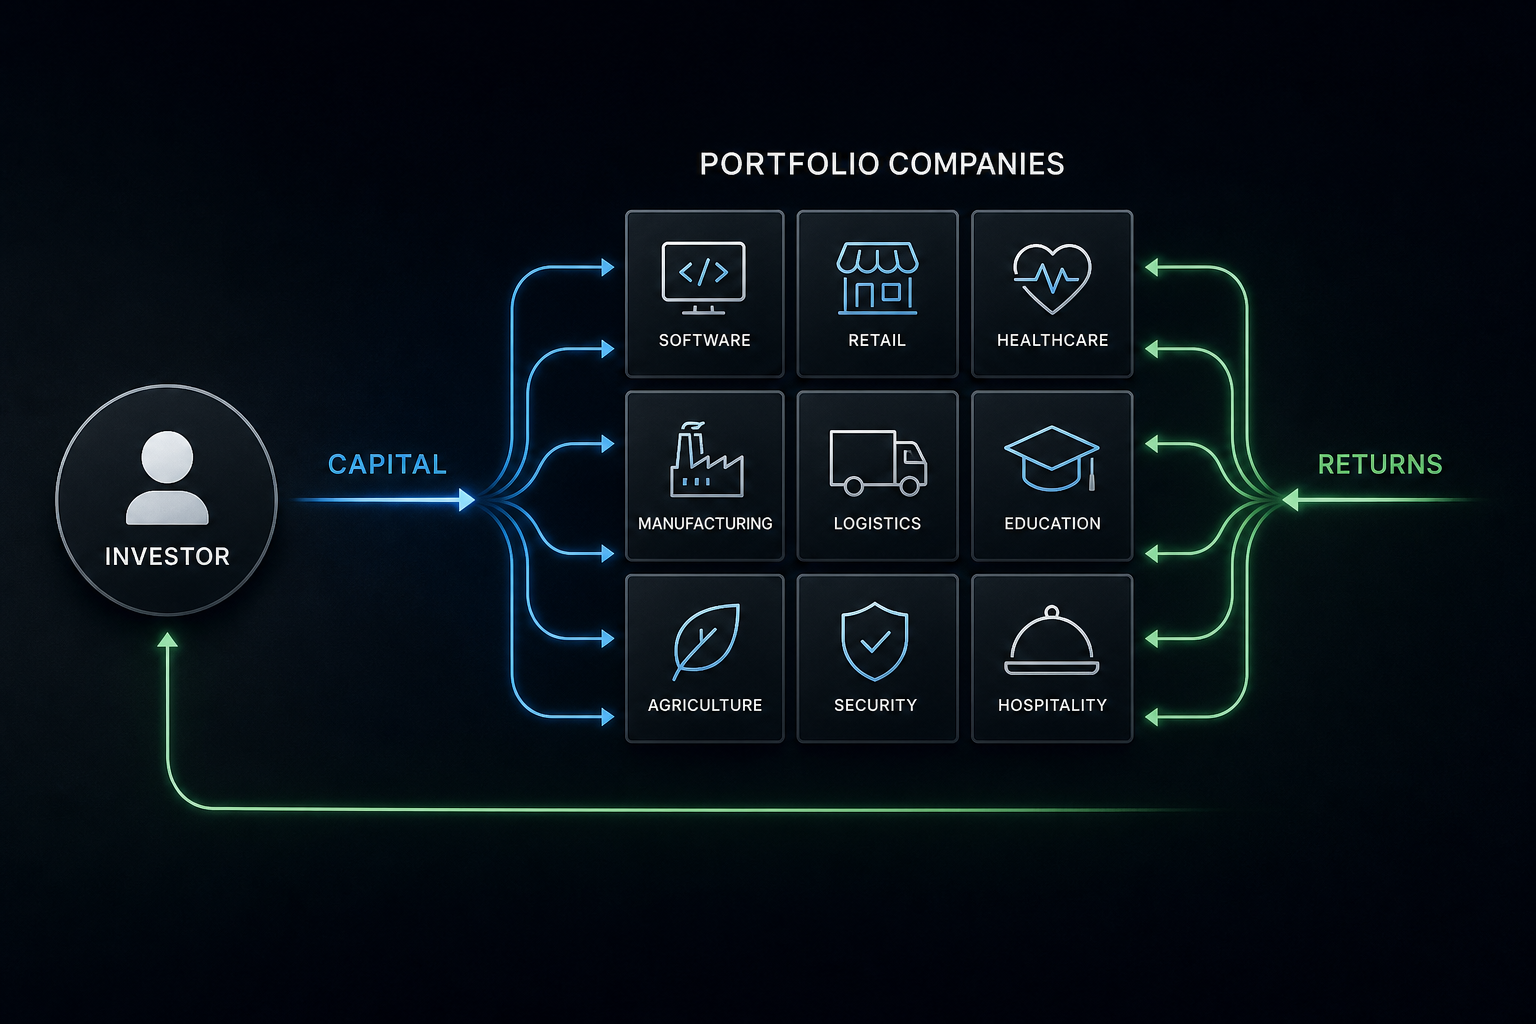
- Low Correlation: The daily sales of a diversified portfolio of restaurants, auto repair shops, and local retailers across the country have a vanishingly low correlation to the S&P 500 or the Barclays Aggregate Bond Index. Performance is driven by micro-economic activity, offering a powerful diversifying element.
- Short Duration: The typical merchant receivable is collected over a period of 6 to 12 months. This high velocity of capital dramatically reduces sensitivity to interest rate fluctuations, a significant uncompensated risk in most fixed-income portfolios today. Capital is returned and can be redeployed, allowing the portfolio to adapt quickly to changing economic conditions.
- Inflationary Pass-Through: Because collections are a percentage of nominal revenue, inflation can, in certain sectors, translate into higher top-line sales figures. This can accelerate the velocity of capital return, providing a potential hedge that is structurally absent in fixed-coupon bonds.
- Granular Diversification: The primary risk is mitigated through scale. An institutional-grade portfolio contains exposure to thousands of individual merchants across myriad industries and geographies. The failure of any single merchant becomes an expected, and manageable, statistical event rather than a catastrophic loss.
A Clear-Eyed View of Risk
No asset offering a structural edge comes without a commensurate risk profile, and intellectual honesty demands we address it directly. The primary risk is, of course, merchant default. This is not an asset for passive investors; it is a domain where the manager's underwriting acumen is paramount.
Sophisticated platforms do not make decisions based on a FICO score. They ingest and analyze terabytes of daily sales data, looking for consistency, seasonality, and other indicators of business health. Diligence on the fund manager, their data infrastructure, and their underwriting track record is therefore the single most important task for an allocator.
Furthermore, while the asset is uncorrelated with market sentiment, it is not entirely divorced from the broader economy. A deep and prolonged recession that suppresses consumer spending across the board would certainly increase collection times and default rates. The thesis is not that merchant receivables are immune to economic gravity, but that their performance is driven by a different and less volatile set of inputs than those that govern public securities.
An Allocation to the Real Economy
Adding merchant receivables to a portfolio is not about chasing yield. It is a strategic decision to allocate capital to an engine of return powered by Main Street, not Wall Street. It offers a short-duration, floating-rate-like exposure to the health of the American consumer, packaged in a structure that allows for institutional levels of diversification and professional management.
For investors who have already built a core portfolio of public assets and traditional alternatives like real estate and private equity, the search for the next intelligent allocation must lead to less efficient, less crowded markets. Merchant receivables, when properly understood and accessed, represent a structurally sound component of a truly diversified modern portfolio.
This article is for informational purposes only and does not constitute investment, legal, or tax advice. The value of investments and the income from them can go down as well as up. Past performance is not a guide to future performance. Consult with a qualified professional before making any financial decisions.
