
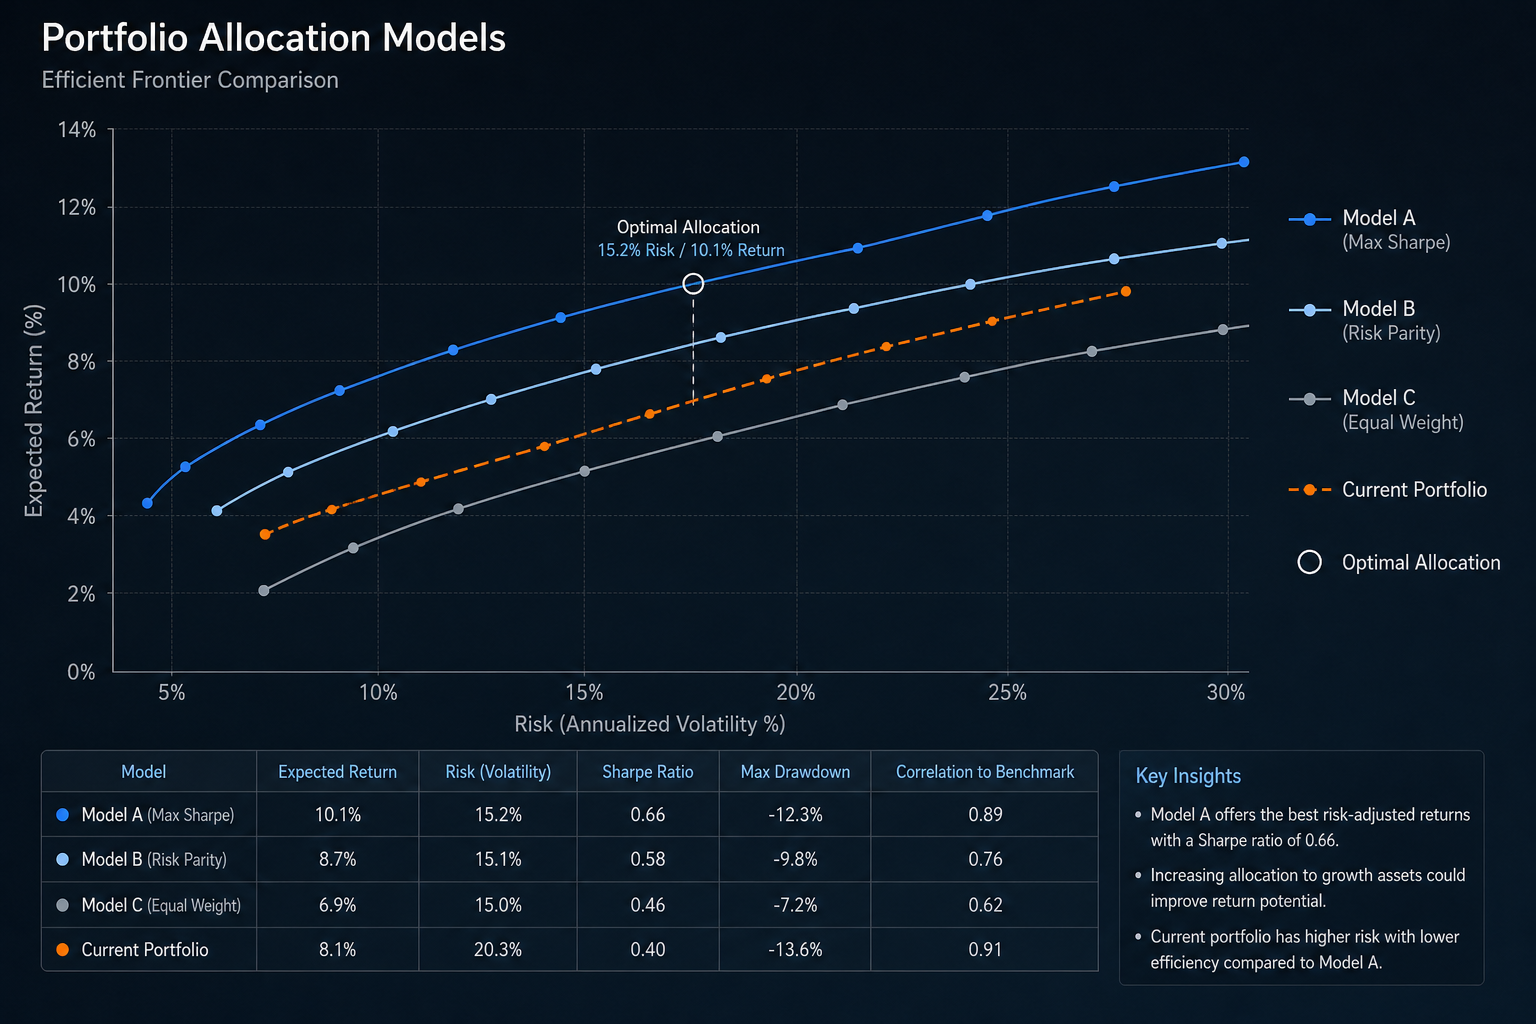
The Foundational Flaw in Modern Portfolios
For decades, the 60/40 portfolio of stocks and bonds was the bedrock of modern asset allocation. Its logic was simple and, for a long time, effective. The model was built on a single, critical assumption: a durable negative correlation between equities and high-quality fixed income. When stocks fell, bonds were expected to rise, providing a crucial ballast that smoothed returns and protected capital. But the purpose of a portfolio is not to adhere to a historical model; it is to preserve and grow wealth through all market environments.
In recent years, that foundational assumption has fractured. During the inflationary environment of 2022, investors watched as both public equities and bonds fell in tandem, delivering punishing losses to supposedly “balanced” portfolios. [VERIFY] The historical negative correlation flipped positive, exposing the fact that both asset classes were ultimately beholden to the same macroeconomic drivers: inflation expectations and central bank policy. For fiduciaries and serious allocators, this was not just a bad year; it was a structural warning. The old model is no longer sufficient.
The Real Definition of Diversification
This market behavior forces us to revisit the first principles of portfolio construction. I do not require every investment to outperform the S&P 500. I require investments that behave differently when the S&P 500 does not. That is the actual definition of diversification, and it is far more difficult to achieve than simply buying a mix of stock and bond ETFs.
True diversification is not about owning different securities. It is about owning different, and preferably uncorrelated, return streams. If the performance of all your assets is ultimately tied to interest rate movements and broad market sentiment, your portfolio is not diversified; it is merely varied. To build genuine resilience, we must look beyond public markets to find assets whose returns are generated by fundamentally different economic engines.
Sourcing Uncorrelated Returns in Private Credit
The search for these return streams has rightly led many advisors to increase allocations to alternatives, particularly private credit. This asset class offers the potential for attractive yields and a lower correlation to public markets. However, not all private credit is created equal. Many strategies, such as direct lending to middle-market companies, can still exhibit significant correlation to the broader economy and credit cycles.
To achieve our goal of genuine diversification, we must drill deeper into niche strategies where the link to public market performance is structurally severed. This is where I have focused a great deal of my own due diligence, and it is where I see a compelling opportunity in merchant receivables.
Merchant Receivables: A Structurally Different Asset Class
Merchant receivables, often associated with merchant cash advances (MCAs), are not loans. An MCA provider purchases a portion of a business’s future revenue streams at a discount. The return is not generated by a fixed interest payment, but by the collection of those future sales. The performance of the asset is therefore tied directly to the top-line revenue of a vast, diversified pool of small and medium-sized operating businesses.
Consider the economic driver here. It is not Wall Street sentiment, Federal Reserve announcements, or quarterly earnings guidance from large-cap companies. It is the daily sales at thousands of restaurants, auto repair shops, healthcare clinics, and retail stores across the country. This is a Main Street economic engine, not a Wall Street one. Consequently, its performance has demonstrated a historically low correlation to the performance of public stocks and bonds. When I evaluate merchant receivables, I do not lead with yield; I lead with this structural non-correlation.
Evaluating the Risk Profile
Of course, no asset is without risk. The primary risk in merchant receivables is the performance and default rate of the underlying small businesses. This is an idiosyncratic, operational risk, which I find preferable to the systemic, macro risks that dominate public markets. This risk is managed through three primary mechanisms:
- Underwriting: Sophisticated data analysis of business cash flows to select stable, performing businesses.
- Diversification: Spreading capital across thousands of individual businesses in different industries and geographies to mitigate the impact of any single failure.
- Structure: Repayments are typically a fixed percentage of daily credit card sales. This means payments automatically adjust to a business’s cash flow. If sales slow, the daily repayment amount decreases, reducing stress on the business and lowering default risk.
Building a Resilient Portfolio for the Next Decade
The breakdown of the 60/40 model was not an anomaly; it was a regime change. Advisors who continue to rely on the simple interplay between stocks and bonds are positioning their clients for future disappointment. My role as a fiduciary is to manage risk first and grow capital second. In an environment where traditional correlations have failed, the most important work we can do is identify and allocate to assets with genuinely different return drivers.
Merchant receivables, as a component of a well-structured private credit allocation, offer exactly that. It is not a replacement for core holdings, but a powerful diversifying tool that can help build a more resilient, all-weather portfolio capable of navigating the complex market cycles ahead.
This article is for informational purposes only and is not intended as investment advice. All investment strategies involve risk, including the possible loss of principal. Private credit and alternative investments are suitable only for accredited investors and carry their own unique risks, including illiquidity. You should consult with a qualified financial advisor to determine if such investments are suitable for your individual circumstances.
