
The Search for Uncorrelated Yield
In a market environment defined by interest rate ambiguity and correlated asset class movements, the intelligent search for yield has moved beyond public markets. For those of us who construct portfolios designed to weather economic cycles, the objective is not to find the next hot trend, but to identify structural advantages—allocations that generate returns from a fundamentally different economic engine. This is the core thesis behind my own allocation to private credit, and specifically, to merchant receivables.
Merchant receivables, often misunderstood as high-risk business loans, are in fact a distinct asset class based on the purchase of future revenue streams. The distinction is critical. This is not a debt instrument but the acquisition of an asset: a predictable, short-term cash flow. Businesses sell a portion of their future credit and debit card sales at a discount to receive immediate working capital. The investor’s return is generated from this discount as the sales are realized. What is new and compelling is the ability for accredited capital to now access this asset class at scale, through platforms that provide professional underwriting and massive diversification.
The Asymmetric Power of Short Duration
The single most compelling structural characteristic of merchant receivables is their extremely short duration. The average term for these assets is typically between six and twelve months [VERIFY]. In an era where the value of long-duration bonds has been decimated by central bank policy, this feature is not just a benefit; it is a primary strategic advantage.
Consider the implications:
- Reduced Interest Rate Risk: While a traditional bond portfolio suffers significant mark-to-market losses when rates rise, a portfolio of short-duration receivables is largely insulated. Capital is returned and recycled so quickly that the portfolio’s yield can adapt to the prevailing rate environment in a matter of quarters, not years. This creates a floating-rate-like exposure without the complexities of swaps or other derivatives.
- Rapid Compounding and Re-Deployment: The velocity of capital is a powerful, and often overlooked, driver of returns. As receivables are paid down daily, that capital becomes immediately available for re-deployment into new opportunities that reflect current market conditions and risk-pricing. This continuous underwriting cycle allows for a dynamic and responsive portfolio.
Intelligent Structure: The Key to Mitigating Risk
The primary risk in this asset class is, of course, merchant default. A naive approach—funding a single business’s receivables—would be speculative. A structured, institutional approach, however, builds a robust portfolio designed to mitigate this risk through several layers of defense.
1. Granular Diversification
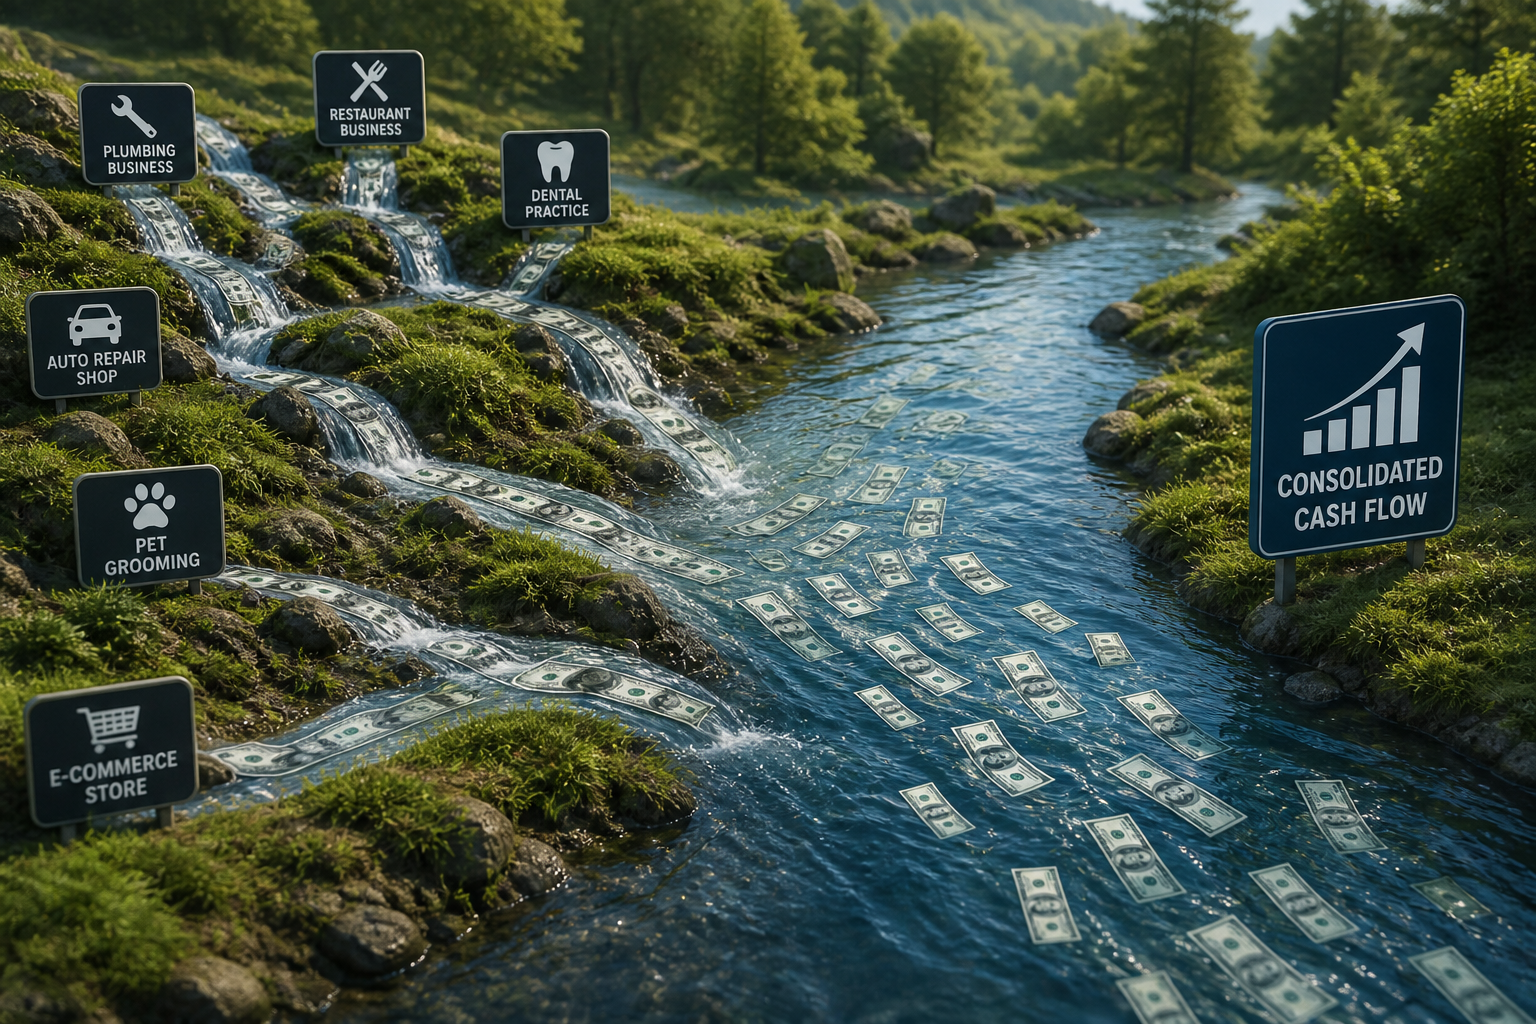
The foundation of risk management here is diversification at a scale unattainable in most other private asset classes. A well-constructed fund provides exposure not to a dozen businesses, but to thousands of them. This diversification is multi-faceted: across geographies, non-cyclical industries (think auto repair, dental services, essential retail), and individual merchant risk profiles. The failure of any single merchant becomes a statistically minor event, not a catastrophic loss.
2. Underwriting Based on Cash Flow, Not FICO
Institutional underwriting in this space is based on the analysis of daily, verified sales data directly from payment processors. The key metric is not the business owner’s personal credit score, but the consistency and predictability of the business’s top-line revenue. This is a crucial distinction from traditional bank lending. We are underwriting the health of the business’s sales, not the owner’s balance sheet.
3. Automated and Senior Collection
The collection mechanism is another point of structural strength. Repayment is not dependent on a business owner writing a check. Rather, a fixed percentage of daily card sales is automatically remitted by the payment processor. This establishes a senior claim on a business’s most vital asset—its incoming revenue—and removes much of the friction and counterparty risk associated with traditional loan servicing.
A Logical Allocation, Not a Speculative Bet
Adding merchant receivables to a portfolio is an allocation to the performance of the broad small-to-medium-sized business economy, decoupled from the sentiment of public equity and bond markets. The return stream is generated by the daily commercial activity of thousands of businesses. For the serious allocator, it represents a compelling opportunity to add a high-yielding, short-duration asset with low correlation to a traditional portfolio. This is not about chasing a fad; it is about identifying a structural inefficiency and allocating capital to it intelligently.
This material is for informational purposes only and does not constitute investment, legal, or tax advice. All investments involve risk, including the potential loss of principal. Private market investments are illiquid and not suitable for all investors.
